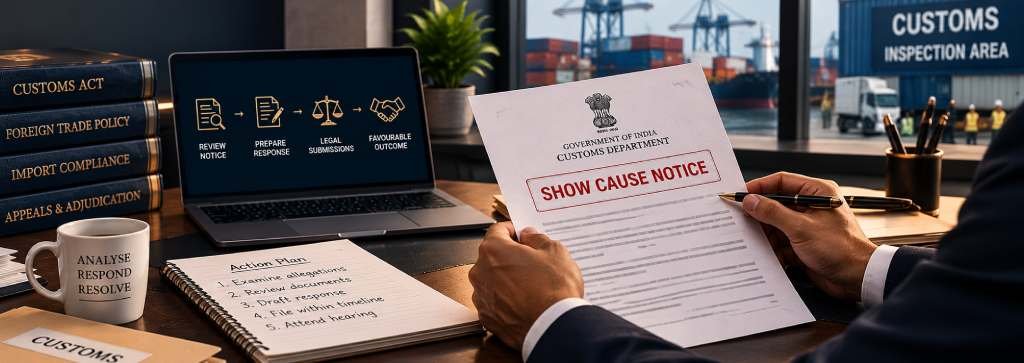
Receiving a Customs Show Cause Notice can be a serious development for an importer, exporter or other person involved in an international trade transaction. Such a notice may raise questions about customs duty, classification, valuation, exemption claims, misdeclaration, confiscation or penalties. A response should therefore be prepared carefully, with close attention to the allegations, supporting documents and applicable provisions of the Customs Act, 1962. Section 124 specifically requires an opportunity to make a representation and a reasonable opportunity of being heard before goods are confiscated or a penalty is imposed.
What Is a Customs Show Cause Notice?
A customs show cause notice, commonly called an SCN, is a formal communication issued by the customs authorities asking a person to explain why a proposed legal action should not be taken. Depending on the circumstances, the proposed action may involve recovery of customs duty, interest, confiscation of goods, imposition of a penalty or other consequences under the applicable customs legislation.
The purpose of an SCN is not simply to communicate a demand. It forms part of the adjudication process. The recipient must be given an opportunity to respond to the allegations before an adverse order is passed in matters covered by Section 124. The notice should identify the grounds for the proposed confiscation or penalty and provide an opportunity for written representation and a hearing. A notice may arise from issues discovered during assessment, post clearance audit, investigation, examination of imported goods or scrutiny of declarations and documents. The exact legal provisions depend on the facts of the transaction.
Why Should an Importer Take an SCN Seriously?
An SCN can have financial and operational consequences. A customs dispute may involve a substantial duty demand, interest, redemption fine or penalty. In some cases, the underlying dispute may also affect future imports, classification practices and the importer’s relationship with customs authorities. Ignoring the notice can weaken the recipient’s position. A proper response gives the importer an opportunity to address the allegations before the adjudicating authority reaches a final decision. The first step should therefore be to identify the deadline mentioned in the notice and understand the allegations before preparing a response. The recipient should also determine whether the notice concerns duty recovery, confiscation, penalty or several issues together.
Examine the Allegations Carefully
A strong response begins with a close reading of the SCN. The importer should identify each allegation separately rather than treating the notice as a single dispute. For example, the customs department may question the declared transaction value, classification of goods, eligibility for an exemption or accuracy of information provided in the Bill of Entry. Each issue requires a separate factual and legal response.
The notice should also be checked for the statutory provisions relied upon by the department. This helps establish the legal basis of the proposed action and allows the recipient to assess whether the provisions have been correctly applied. The authority identified in the notice should also be verified. CBIC guidance indicates the importance of identifying the authority responsible for adjudication and ensuring the noticee has a fair opportunity to present its case.
Check the Relevant Time Limits
Limitation is an important issue in customs proceedings. Section 28 of the Customs Act deals with recovery of duties not levied, not paid, short levied, short paid or erroneously refunded, along with certain interest liabilities. Under the current statutory framework, Section 28 generally provides a two year period for serving a notice in cases falling outside specified circumstances involving collusion, wilful misstatement or suppression of facts. Different rules apply where such circumstances are alleged.
This makes it important to examine the relevant date, date of import, date of assessment and date of service of the notice. The limitation argument must be assessed alongside the specific allegations made by customs. An importer should not assume a notice is valid simply because it has been issued by a customs authority. Procedural requirements and statutory limitation can become important parts of the defence.
Gather the Relevant Import Documents
The factual record is often central to a customs dispute. The response should be supported by documents capable of establishing how the transaction actually occurred. Depending on the allegations, relevant records may include the Bill of Entry, commercial invoice, packing list, purchase order, purchase agreement, bill of lading, insurance documents, payment records, catalogue material and technical literature relating to the goods.
Where classification is disputed, product specifications and technical literature can be particularly useful. Where valuation is questioned, the importer may need to produce documents explaining the commercial terms, relationship between the parties, pricing structure and payment arrangements. The objective should be to connect each factual statement in the reply with reliable documentary evidence.
Respond to Each Allegation Separately
A customs reply should be structured around the allegations in the notice. A general denial may not adequately address the department’s case. Suppose the SCN alleges incorrect classification. The response should explain the characteristics of the product, the relevant tariff heading and why the proposed classification is incorrect. Supporting technical documents can strengthen the explanation.
Similarly, if the dispute concerns valuation, the importer should explain the basis of the declared value and address the department’s reasons for questioning it. A clear allegation followed by a factual explanation, legal position and supporting evidence usually makes a response easier for the adjudicating authority to examine.
Examine the Duty Demand and Penalty Separately
A customs dispute may involve several components. The importer should therefore examine the duty demand separately from interest, confiscation and penalty proposals. The legal basis for recovering duty may differ from the basis for imposing a penalty. Similarly, the circumstances supporting confiscation may require separate consideration. Section 124 provides procedural safeguards before confiscation or penalty, including written notice, an opportunity to make a representation and a reasonable opportunity of being heard. The response should therefore address each proposed consequence rather than focusing only on the underlying duty demand.
Consider Whether Pre Notice Consultation Applies
In certain duty recovery proceedings, the Customs Act requires pre notice consultation before an SCN is issued. Section 28 contains a provision requiring the proper officer to conduct pre notice consultation with the person chargeable with duty or interest in the prescribed manner. The Customs (Pre Notice Consultation) Regulations, 2018 provide a framework for such consultation in specified circumstances. The regulations also contemplate an opportunity for the person concerned to make submissions and indicate whether a personal hearing is desired. Whether the requirement applies to a particular notice depends on the nature of the proceedings. It should therefore be examined based on the statutory provision under which the demand is proposed.
Request a Personal Hearing Where Appropriate
A written reply is not always the end of the process. Section 124 recognises a reasonable opportunity of being heard in matters involving confiscation or penalty. Where the factual or legal issues are complex, a personal hearing can provide an opportunity to clarify documents, explain technical matters and respond to points raised by the adjudicating authority. The request for a hearing should be made clearly in the written response where appropriate. The recipient should also maintain a proper record of submissions made during the hearing.
Seek Professional Assistance for Complex Notices
Customs law involves detailed provisions concerning classification, valuation, exemptions, import procedures, confiscation and penalties. A complex SCN may also involve substantial financial exposure. Businesses may consider obtaining advice from a consumer protection attorney where the dispute has broader implications involving product compliance or consumer related issues alongside customs concerns.
For disputes primarily involving customs duty, classification, valuation or import compliance, specialist legal and tax advice can help in analysing the allegations, limitation, evidence and available remedies. A taxation law firms may also be relevant where the customs dispute has significant tax implications. Professional assistance is particularly useful where the notice alleges suppression of facts, willful misstatement, undervaluation, misclassification or deliberate evasion. Such allegations can have more serious consequences than an ordinary assessment disagreement.
Avoid Unsupported Admissions
An importer should be careful before admitting an allegation in correspondence with customs authorities. A factual clarification is different from an admission of legal liability. The response should use precise language and should not concede a point simply because correcting an error appears convenient. Where an error has genuinely occurred, the appropriate approach depends on the circumstances, including the nature of the error, applicable statutory provisions, timing and potential consequences. The response should be based on the complete factual record rather than an immediate reaction to the notice.
What Happens After the Reply?
After considering the response and other material available on record, the adjudicating authority may proceed to determine the issues raised in the proceedings. The final order may confirm, modify or drop the proposed demand or other action, depending on the facts and applicable law. The Customs Act also provides for adjudication and appeal mechanisms, although the appropriate remedy depends on the nature of the order and the circumstances of the case. A customs dispute therefore does not necessarily end with the SCN. The reply is an important stage in the wider adjudication process.
Common Mistakes to Avoid
One common mistake is responding without first understanding the statutory basis of the notice. Another is submitting a reply without documentary evidence supporting important factual claims. Missing the response deadline can also create procedural difficulties. Businesses should maintain a central record of notices received and track deadlines carefully. It is equally important to avoid submitting lengthy material without explaining its relevance. A well-organized response should help the adjudicating authority understand the transaction, the dispute and the reasons why the proposed action should not be sustained.
Conclusion
A Customs Show Cause Notice should be treated as an important stage in customs adjudication rather than as routine correspondence. A timely and evidence based response can help an importer explain the transaction, challenge incorrect allegations and protect its legal position.
The most effective approach is to examine the statutory provisions, limitation, factual allegations and supporting evidence together. Businesses should also maintain proper import documentation and review recurring customs issues to reduce the likelihood of future disputes. Where the notice involves significant financial exposure, complex valuation or classification questions, or allegations of deliberate misstatement or suppression, obtaining specialised legal advice at an early stage can be particularly important.